Multi-layer acquisition
The investor needs several sources of capital to close and execute the business plan. Each layer should have a defined role and repayment source.
Creative Funding, Capital Strategist & Capital Stacking Consultant
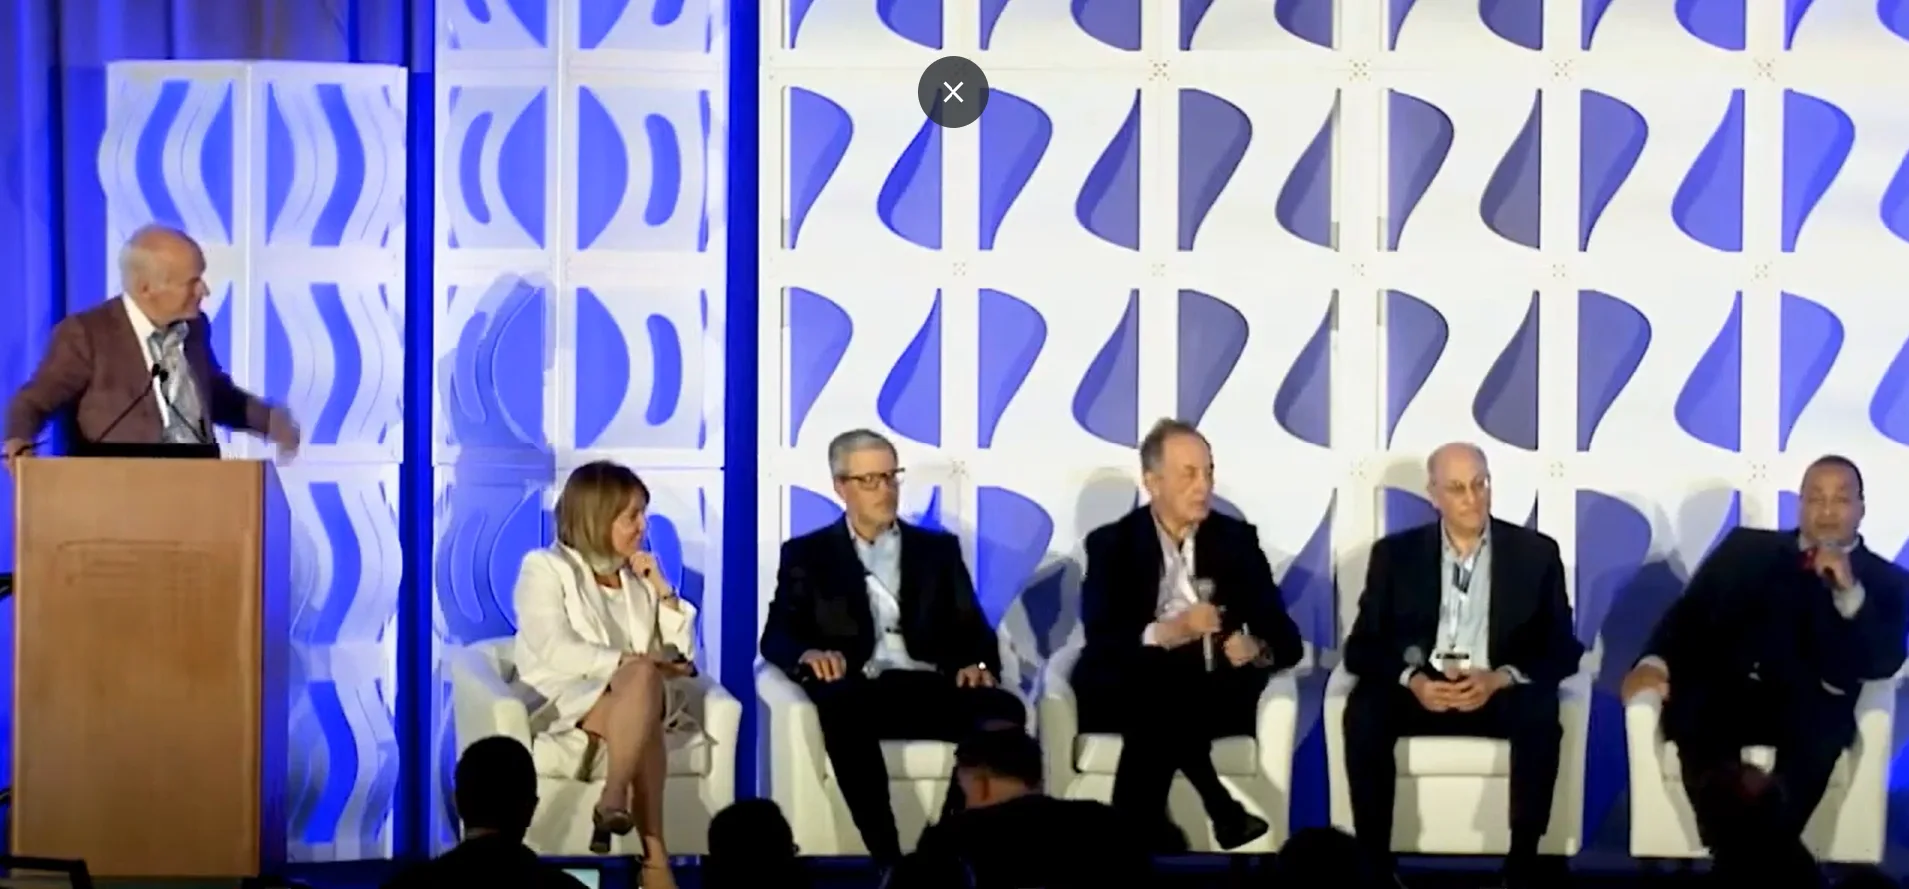
Romeo Sykes works with entrepreneurs, business owners, and real estate investors on capital structures that can involve business funding, private money, bridge financing, DSCR loans, rehabilitation, construction, acquisitions, and other transaction-oriented needs. His profile also includes published video appearances that provide context for the legal, accounting, family-office, and real estate conversations surrounding his work.
Prospects with business, acquisition, or real estate transactions that may require more than a single conventional financing path.
Capital stack, collateral and property economics, business cash flow, transaction timing, liquidity, exit strategy, and the provider-specific facts required for underwriting.
Romeo’s strategic role does not replace the independent provider’s credit decision. Any financing remains subject to provider eligibility, documentation, pricing, and final terms.
Complex opportunities can involve several capital needs at once. An acquisition might require earnest money, acquisition debt, rehabilitation funds, reserves, and permanent refinancing. A growing business may need equipment and operating capital on different repayment horizons.
Romeo’s published media places him in conversations involving title and real estate law, commercial property, family-office capital, foreclosure strategy, accounting, acquisitions, and fund management. Those topics matter because financing does not operate in isolation from transaction structure.
A complicated opportunity becomes easier to evaluate when the facts are organized into acquisition basis, budget, operating cash flow, collateral, reserves, experience, and exit.
Purpose. These videos illustrate Romeo Sykes’ professional background, industry participation, educational activities, and exposure to experienced business, real estate, finance, and institutional professionals.
No implied endorsement. Appearances, interviews, events, or relationships involving any person or organization—including executives, companies, family offices, brokerages, and investment firms—do not constitute an endorsement, partnership, investment or financing commitment, sponsorship, regulatory approval, or recommendation of Romeo Sykes, Nationwide Business Funding, Dominion Capital Management, Inc., or any affiliated initiative unless expressly stated in a separate written agreement.
Securities. Nationwide Business Funding does not offer or sell securities through this website. Any activities of Dominion Capital Management, Inc. are separate and subject to Dominion’s own offering documents, eligibility requirements, and compliance procedures.
The investor needs several sources of capital to close and execute the business plan. Each layer should have a defined role and repayment source.
An operating company is acquiring both a business and property. Business cash flow, property value, occupancy, and transaction structure can point to more than one financing lane.
Private or bridge capital may solve a timing problem, but speed should be paired with a credible exit and sufficient reserves.
Treat each source as a separate job. A stack can include senior debt, subordinate or bridge capital where appropriate, and borrower or investor equity; a business-plus-real-estate transaction may also use separate facilities for the operating company and the property. Each layer should have a defined purpose, collateral position, payment obligation, maturity, and repayment or exit source.
Temporary capital is usually the layer meant to bridge a specific gap rather than stay in place for the full life of the asset or business plan. Before using it, identify the expected exit—such as a sale, refinance into permanent financing, collection of receivables, asset disposition, or another documented source—and make sure the timeline is realistic.
Yes. Existing liens, title defects, ownership questions, collateral conflicts, required releases, entity documents, and property-specific issues can affect what a provider can secure and when it can close. These items should be surfaced early because they may require payoff, correction, consent, subordination, or appropriate legal and title review.
Build the downside case before closing. The plan should account for reserves, carrying costs, budget overruns, extension or maturity terms, and the effect of a delayed exit on cash flow. If a modest delay breaks the transaction, the capital stack may be too tight.
More than one source can make sense when the transaction has different uses of funds with different timing, collateral, or repayment periods—for example, acquisition money, rehabilitation or construction funds, operating capital, and permanent takeout financing. More layers are not automatically better; each added source should solve a specific problem without creating an unmanageable payment, lien, or closing burden.
Bring the facts that make the transaction understandable: the amount and purpose, timing, acquisition basis or purchase price, project or rehabilitation budget where relevant, business cash flow, property or collateral details, available reserves or borrower cash, experience, existing debt or liens, and the expected repayment or exit. The more clearly the uses and sources are separated, the easier it is to evaluate possible structures without treating preliminary possibilities as approvals.
These pages address adjacent but distinct funding questions. Use them to compare structure without mixing separate search intents.
Provide the core business or transaction information and a representative can follow up about possible next steps.
Choose $10 Experian or $20 TriMerge and have your credit review AI-merged with your funding profile so NBF can evaluate the file and architect your capital strategy. After payment: complete the funding profile and any required credit-report authorization, then book the funding consultation. Payment alone does not authorize a consumer credit pull or guarantee approval, amount, pricing, or terms.